


Every year around this time, I get some version of the same question.
A patient finishes their visit, grabs their purse, gets halfway to the door… and then turns around. “Okay, Ashley, real quick. Open enrollment. Which plan do I pick?”
And then they pull out their phone and show me fourteen open tabs of plans that all look exactly the same, except for the numbers that make your eyes cross. Premiums. Deductibles. Coinsurance. Out-of-pocket maximums. Bronze, Silver, Gold, and something called a “catastrophic” plan that honestly sounds like a threat.
I’m a nurse practitioner, not an insurance agent, so I can’t pick your plan for you.
But I can tell you the one thing I see people forget almost every single year: they shop for the hospital stay they hope never happens and forget about the everyday care they’ll actually use.
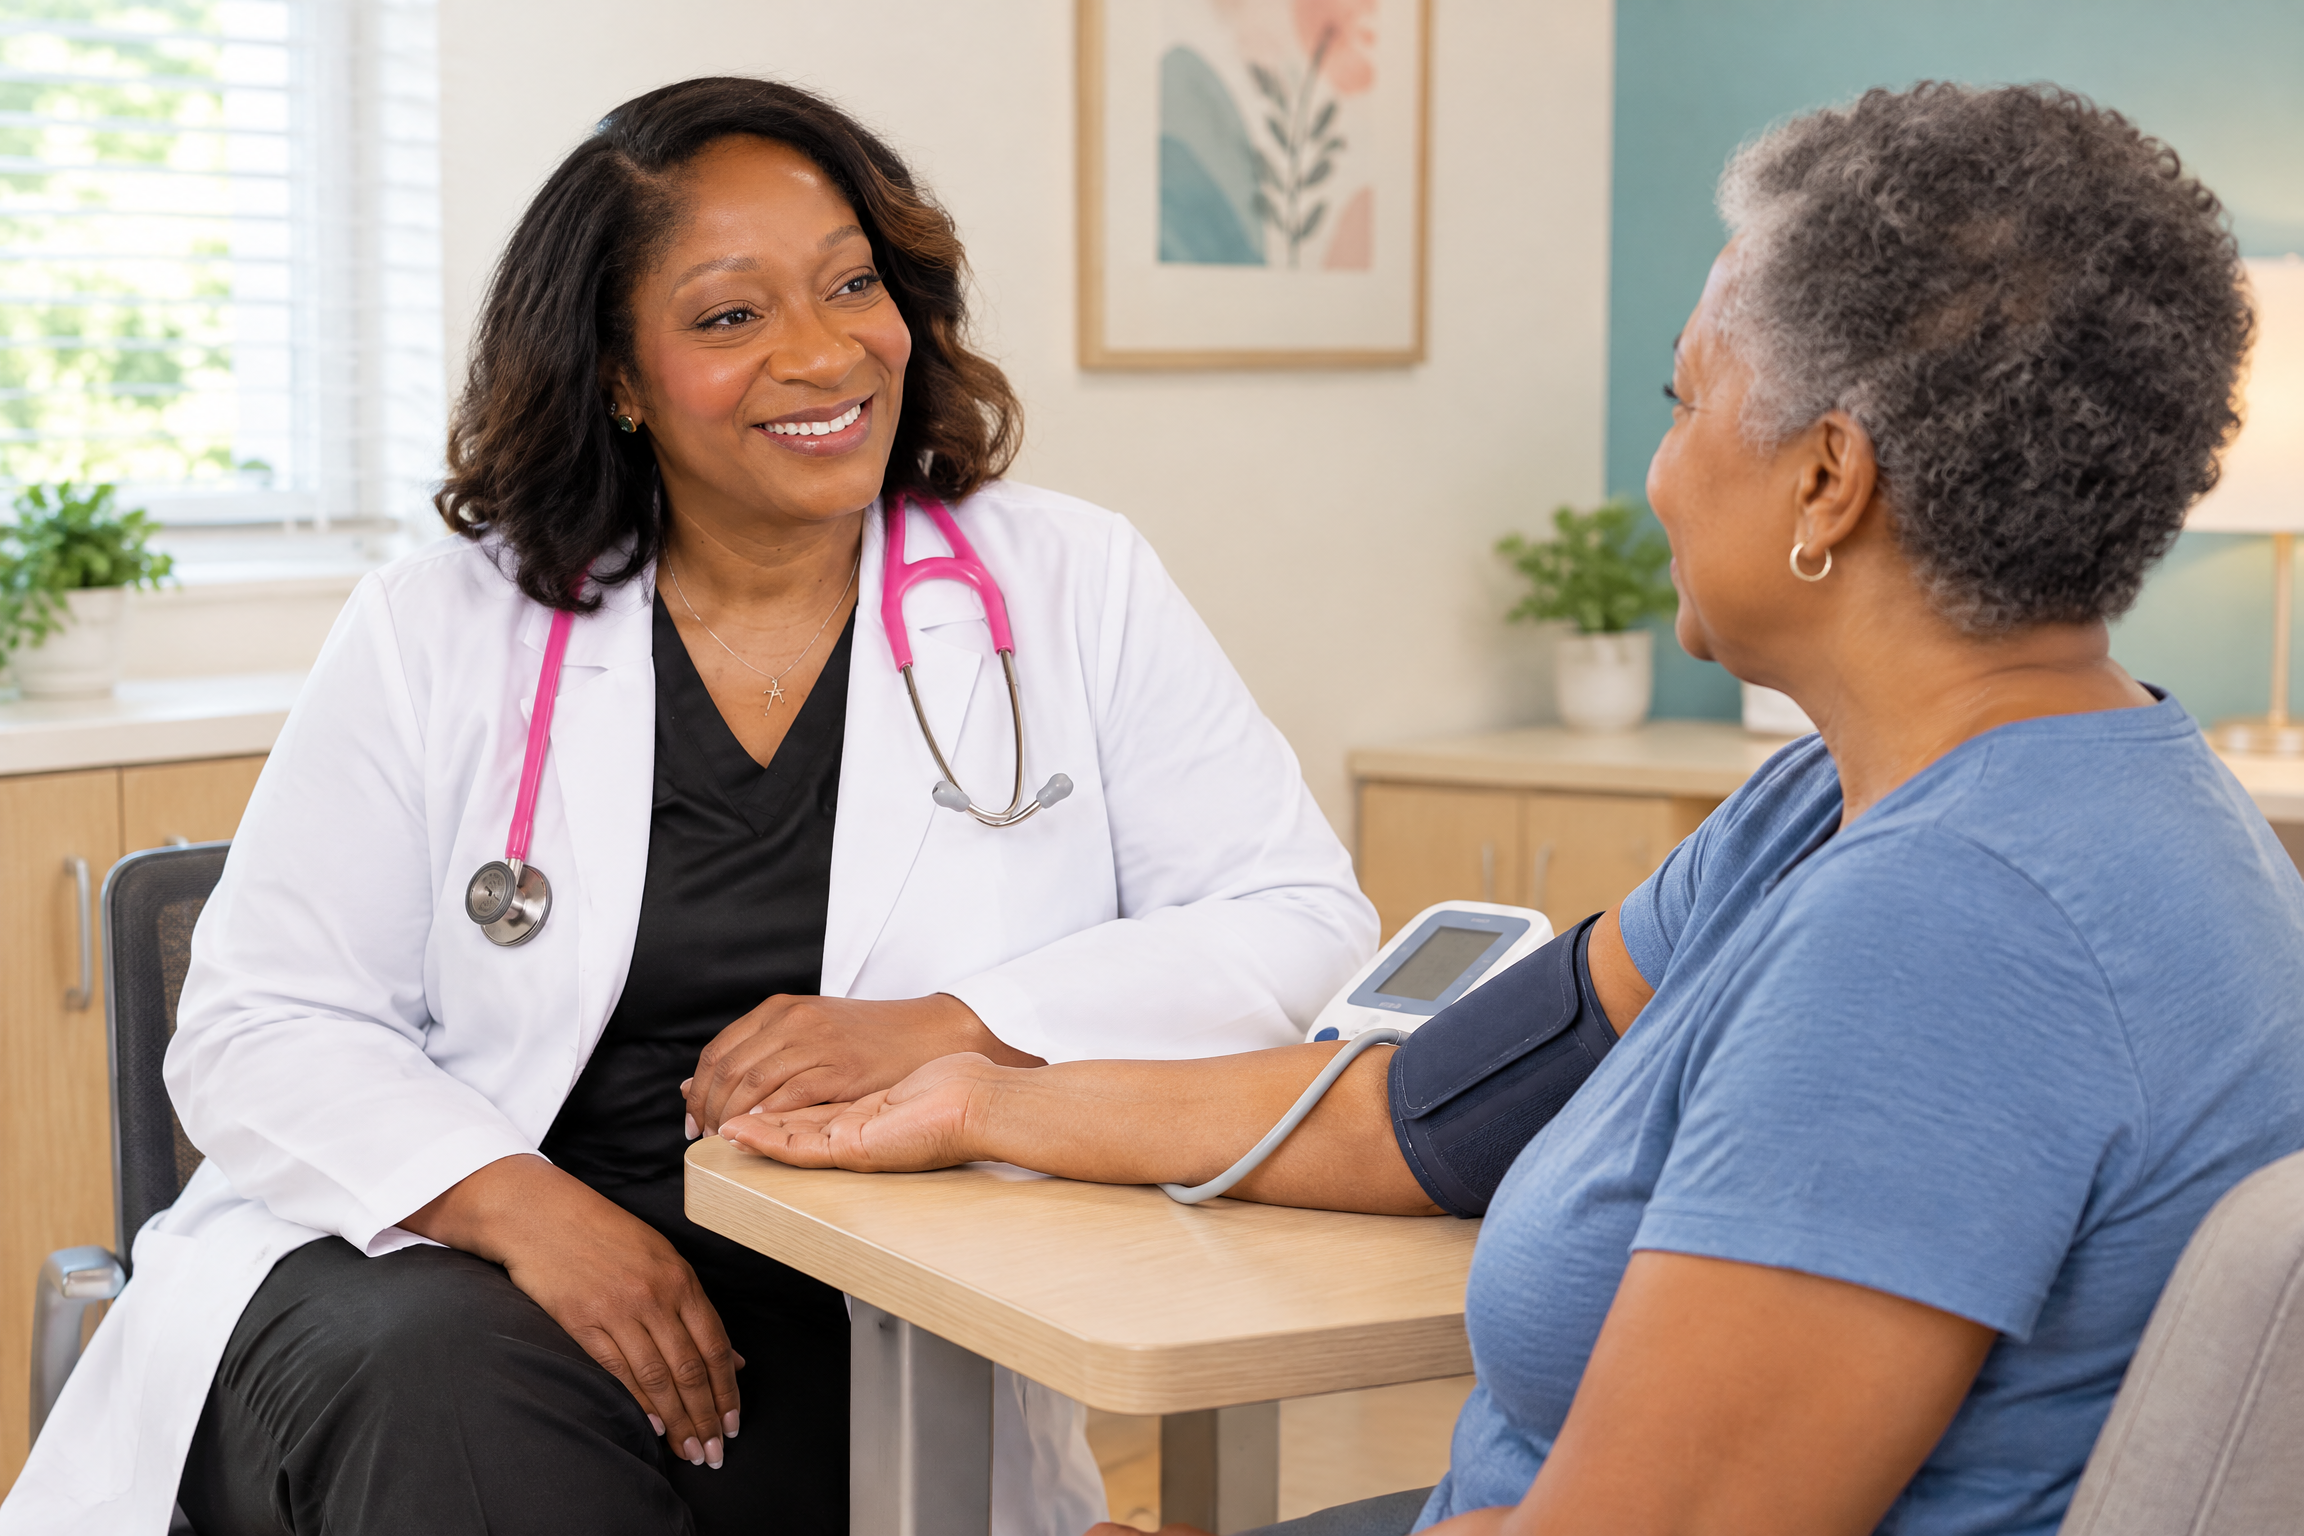
That everyday care? That’s primary care. And it should be part of your open enrollment game plan.
Talk to Us About Primary Care in Jacksonville, FL
Open Enrollment Dates You Need to Know
First things first. Put these on your calendar (or your fridge, or wherever you keep the important stuff).
If you buy your own insurance (HealthCare.gov)
Florida uses HealthCare.gov, and open enrollment for 2027 coverage runs November 1, 2026 through January 15, 2027.
- Enroll by December 15, 2026 if you want coverage to start January 1.
- Enroll December 16 – January 15 and coverage generally starts February 1.
- After January 15, you’ll need a qualifying life event (like losing a job, moving, getting married, or having a baby) to enroll.
Quick heads up: there’s been some back-and-forth in the courts about shortening this window. Always double-check the dates on HealthCare.gov before you wait until the last minute. Better yet, just don’t wait until the last minute.
But there are a ton of other symptoms too.
If you have Medicare
Medicare open enrollment is already happening. It runs October 15 through December 7, 2026, and any changes you make start January 1, 2027.
If you get insurance through work
Your employer sets its own open enrollment window, and it’s usually shorter than you think. Check your email (yes, even the ones from HR you’ve been ignoring).
What’s Different This Year (The Honest Part)
I’m going to be real with you, because nobody likes a surprise bill.
The extra federal help that made Marketplace plans cheaper from 2021 through 2025 expired at the end of 2025, and it hasn’t been renewed for 2027. That means the old income limit is back. If your household earns more than 400% of the federal poverty level (about $63,840 for a single person or $132,000 for a family of four), you don’t get any premium help at all. Not a smaller amount. None.
On top of that, a lot of insurers are raising premiums again for 2027.
So if your plan felt expensive last year, I’m sorry to say it may feel that way again. Which is exactly why it matters so much that whatever you pay for actually gets you care you can use.
The Mistake I See Every Year
Here’s what usually happens. People look at the monthly premium, pick the lowest one, and call it a day.
Then in March they get a sinus infection, call the office, and find out they’re paying for that visit out of pocket because they haven’t met their $7,000 deductible.
Or they finally come in for those nagging headaches and blurry vision, and we find high blood pressure that’s been quietly building for who knows how long, because they skipped checkups when money got tight.
And I get it. No judgment from me. When insurance costs this much, of course you’re not running to the doctor for every little thing.
But primary care is where we catch the quiet problems early. It’s your sick visits, your annual physical, your lab work, your blood pressure checks, your medication refills, and the person who actually knows your history when something feels off. Skipping it is how small, treatable issues turn into big, expensive ones.
What to Look For in a Plan If You Care About Primary Care
Before you hit “enroll,” grab a cup of coffee and look for these things:
- Is your primary care provider in network? Don’t assume. Look them up in the plan’s directory, or call the office and ask.
- What do sick visits cost before you meet your deductible? Some plans give you a flat copay. Others make you pay the full price until the deductible is met.
- Is preventive care covered? Most Marketplace plans cover certain preventive services, like your annual wellness visit and some screenings, at no cost when you see an in-network provider.
- How are labs covered? Labs can add up fast, especially if you have a chronic condition.
- What about your prescriptions? Check that your medications are on the plan’s drug list.
- Can you see your provider quickly? A great plan doesn’t help much if the next appointment is three weeks away.
Where Direct Primary Care Fits In
This is the part I love talking about, because it’s the reason I built NOLA Care the way I did.
Direct Primary Care (DPC) is a membership. You pay one flat monthly fee, and you get access to your primary care provider without copays or surprise bills for your everyday care.
At NOLA Care, that looks like:
- $149/month for adults and $50/month for kids (plus a one-time $175 enrollment fee)
- Routine labs like a CBC, CMP, and lipid panel included
- Same-day and next-day appointments, in person or virtual
- A provider who actually knows your name and your story
Now, an important note: DPC is not insurance. You’ll still want coverage for the big stuff, like hospital stays, specialists, surgery, and emergencies.
That’s why a lot of my patients pair a DPC membership with a lower-premium plan, like a high-deductible, bronze, or catastrophic plan. The insurance protects you from the worst-case scenario. The membership takes care of everything in between. (If you want to see how those plans compare side by side, I broke it all down in this blog.)
There’s also some good news on the money side. Starting in 2026, a new federal law lets people with a high-deductible plan and a Health Savings Account (HSA) use those HSA dollars for certain direct primary care memberships of up to $150 a month for an individual. The rules are specific, so check with your HSA administrator or tax professional to see what applies to you.
We Take Insurance, Too
NOLA Care is a hybrid practice, which means you don’t have to choose between a membership and your insurance.
We accept most major insurance plans, including Medicare, Cigna, CHAMPVA, and Curative. So if you’re on Medicare and comparing plans right now, make sure the one you choose lets you keep seeing the provider you trust.
Not sure if we take your plan? Give us a call before you enroll. We’re happy to check.
And Since I Know You Have Questions…
Let’s knock some of these out before you end up three hours deep in a Google rabbit hole.
Do I really need a primary care provider if I’m healthy?
Yes. Honestly, especially if you’re healthy. That’s when we get your baseline numbers so we can tell when something changes. A lot of what I diagnose in adults 25-40 shows up before people feel sick.
Can I just do Direct Primary Care instead of insurance?
Some people do, but I always recommend having some kind of coverage for emergencies, hospital stays, and specialists. DPC covers your everyday primary care. It doesn’t cover a trip to the ER or a broken leg.
Is my annual physical free with insurance?
Many plans cover a yearly preventive visit at no cost when you see an in-network provider. But if you bring up a new problem during that visit, like a new pain or a medication concern, it may be billed as a separate visit. Ask your plan how they handle it. If you need a new one and are near Bartram Park, Orange Park, Jacksonville, or St Johns and want to come in to our Jacksonville office – give us a call.
I missed the deadline. Now what?
If you’ve had a big life change, like losing your job, moving, getting married, or having a baby, you may qualify for a Special Enrollment Period. And remember, a DPC membership doesn’t have an enrollment window. You can join anytime.
How do I know if this is a I’m on Medicare. Can I still come to NOLA Care?
Yes! We now accept Medicare. Just make sure the plan you choose during open enrollment includes us.
Your Open Enrollment Cheat Sheet
- Print this, screenshot it, or send it to the group chat:
- Consider pairing a lower-premium plan with a DPC membership
- Mark your deadline: December 7 (Medicare) or December 15 (Marketplace, for a January 1 start)
- Make sure your primary care provider is in network
- Look at what a sick visit costs before your deductible, not just the monthly premium
- Check your prescriptions and labs
- Ask yourself how often you actually go to the doctor, and how often you should
And of course, the hundred-dollar question…
When Should You See A Doctor For A Sinus Infection?
Look, I’m with you. I know not every stuffy nose needs a doctor’s appointment. And you can’t always take off work every time you wake up with a scratchy throat.
Sometimes you really do cough once, notice a little congestion, and then realize it’s because you slept with the fan on all night.
So, I want you to have a cheat sheet for when you’re more likely to need to come in.
- If you’ve been battling sinus infection symptoms for more than 10 days and they’re not getting better
- If your symptoms suddenly spike or get much worse
- If you become wheezy or it’s hard to breathe
- If it’s a young child or senior who’s showing symptoms
- Or if you have an underlying condition that may also be coming into play
That’s when it’s time to come in and let us take a look.
What Does Sinus Treatment Look Like?
If you’re dealing with a viral infection, most of the time it just needs to run its course.
But you don’t need to suffer along. You can use over-the-counter medications for pain, headaches, and that uncomfortable nasal congestion.
If you’re dealing with a bacterial sinus infection, then we’ll need to test to see which antibiotic is the best treatment for you.
Looking for Primary Care in Jacksonville, FL?
Whether you’re picking a new plan, switching to Medicare, or finally ready to stop going without a regular provider, we’re here to help you figure it out.
My team and I at NOLA Care offer full-service primary care in Jacksonville, serving Bartram Park, Mandarin, St. Johns, and the surrounding area. Use your insurance, join a membership, or do both. However you get here, you’ll be treated like a person, not a policy number.
Make an appointment or explore our memberships before open enrollment closes.
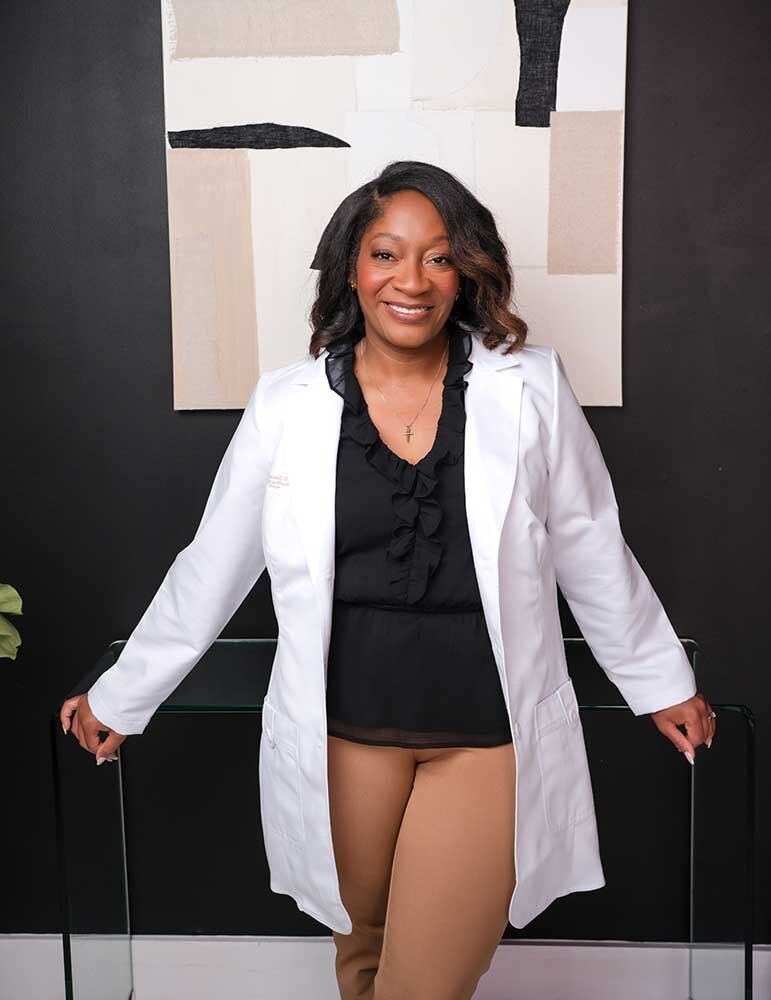
Hey there, I’m Ashley Roussell, DNP, FNP-C
I started NOLA Care to make sure quality healthcare was available for everyone in Jacksonville. That’s why we offer direct primary care (DPC) and affordable healthcare memberships for the whole family.
Sinus pressure is treatable, but only with the proper diagnosis. It’s time to take this offline and into an appointment. You deserve to have answers and a primary care provider who treats you like a person, not another slot on their calendar. If you’re ready, my team and I are here for you.
